Cargo Insurance for Ceramic Shipments: How Risk Divides on the Water
- Share
- Issue Time
- Sep 10,2026
Summary
Ceramic is heavy, stackable and breakable — which makes the voyage, not the kiln, where most loss risk lives. This guide explains where responsibility changes hands under common trade terms, what a cargo policy actually covers, and why the claim file, not the premium, decides whether a transit loss stays a story or becomes a bill.
The Problem: The Kiln Survived, the Voyage Didn't
A ceramic order passes its final inspection with a clean report, loads into the container, and for a few weeks nobody can touch it. Then the voyage happens — lifts, shifts, weather, handling at two or three terminals — and a small share of shipments arrive with a carton or two that tell a different story. Transit loss on tableware is rarely dramatic; it is a cracked bowl here, a crushed corner there, discovered at the receiving dock weeks after everyone has moved on. What separates a managed outcome from an ugly one is not luck and not the premium paid — it is whether the risk was placed deliberately, with the right cover and the documents to use it. Insurance is the least frequent claim on a sourcing budget and the one that repays attention with the least warning.
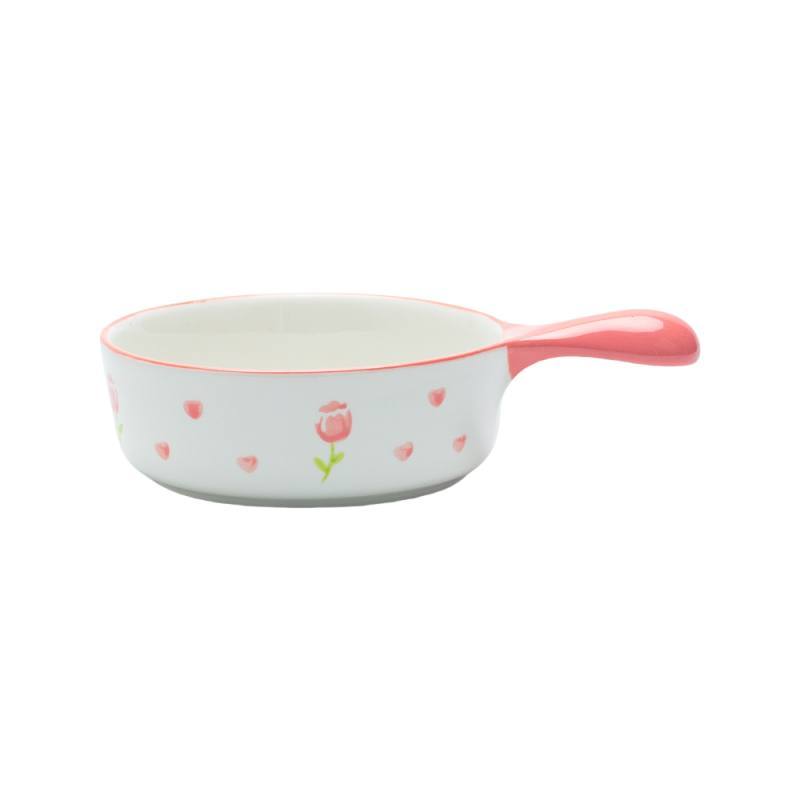
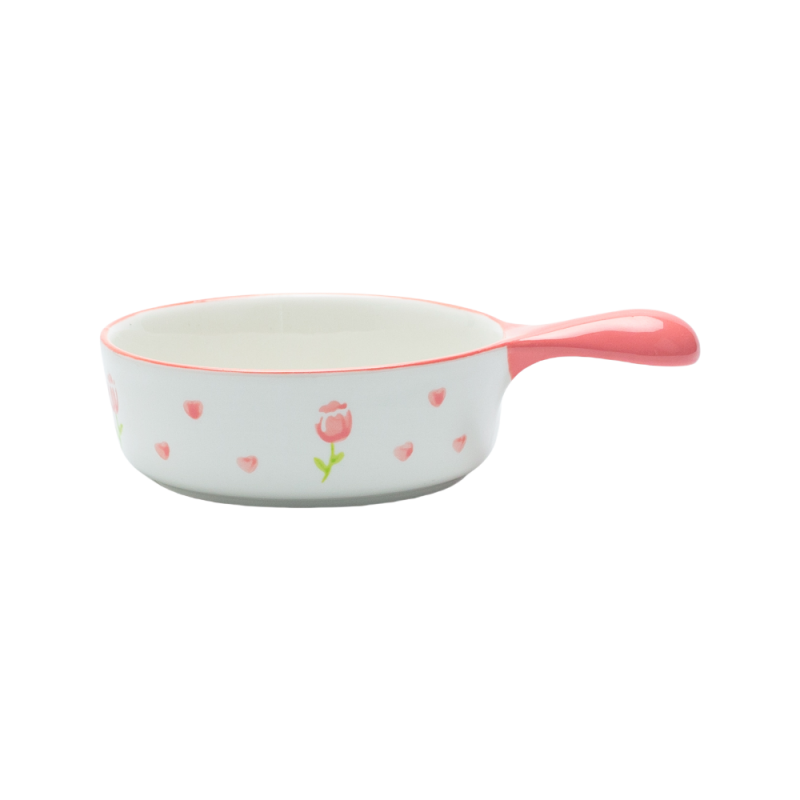
Products in this guide: Cute Ceramic Bowl with Handle · Ceramic Butter Dish with Cover and Knife Slot
Where This Fits in the Sourcing Chain
Insurance sits downstream of the commercial terms chosen at quotation and upstream of the shipment file that carries the claim if one comes. The container inquiry checklist shows how to get that first quote right. The forwarder arranges or advises the cover in most programs. The freight forwarder guide explains how to choose and manage the logistics partner. The full chain follows the standard sourcing map. See the full ceramic sourcing process map.
Where Responsibility Actually Changes Hands
Trade terms are, at heart, a map of who owns the risk on every metre of the journey. FOB: the seller delivers the goods on board at the origin port; from that point the voyage — and its risks — belong to the buyer. CIF: the seller also contracts and pays for carriage and insurance to the destination port; but note what CIF actually promises — the minimum cover, in the seller's name, for the buyer's benefit. The risk still transfers at origin, which surprises buyers who read CIF as "seller pays for everything until my port". DAP: the seller carries the risk to the named destination place, which shifts the transit exposure back toward the seller's side of the table. None of these choices is universally right — they are a match between who controls the freight and who wants to own the risk. The working rule: whoever controls the freight decision should control the insurance decision too, because the two move together.
What a Cargo Policy Covers — and What It Asks of You
Marine cargo policies are built around conditions — families of cover with different breadth — and the name on the certificate matters less than what the condition actually includes for breakage-prone goods. For ceramics the conversation with the insurer is specific: breakage is the named enemy, and cover for it depends heavily on packing being adequate for the voyage. Two mechanism-level truths are worth holding onto. First, a policy expects the insured to behave as a careful uninsured owner would — packing that a surveyor would call sound, declared values that reflect the real commercial value. Second, exclusions cluster around the predictable: inadequate packing, pre-shipment damage that existed before loading, and ordinary loss in weight or volume. That is why the packing specification and the insurance conversation belong in the same meeting — the strongest premium negotiating position is a documented, drop-tested carton standard. The spec freeze guide explains how to lock artwork and packing files between orders.
The Claim File: Documents Decide
When a carton fails, the outcome is decided by the file, not the feelings. The pieces that matter are gathered in days: notice to the carrier or insurer within the timeline the document set specifies; evidence — photographs of the damaged cartons as found, before restacking, plus the container's state on opening; the survey, where the insurer's agent examines the goods and issues a report; and the paper chain — bill of lading, commercial invoice, packing list, and the inspection report that shows the goods left the factory sound. The shipment file guide explains how to read inspection reports and transport documents. That last document is the quiet hero: a pre-shipment inspection report converts "the goods were damaged somehow" into "the goods were sound at origin, protected by specified packing, and damaged in transit" — which is exactly the sentence a claim needs.
Pricing Logic Without the Guesswork
Premiums are priced from declared value, route, packing standard and claims history — and buyers do not need the tariff to act on that. The levers that genuinely move cost are the ones already discussed: realistic declared values, documented packing standards, and a clean claims file built by reporting properly rather than absorbing small losses silently or inflating claims defensively. On repeat lanes, the annual review is where the cover gets tuned: last year's volumes, any route changes, and the claims experience all feed the next term sheet. The annual price review guide explains how renegotiation works with data.
The Habit That Ties It Together
The habit is a one-page risk line per shipment: terms chosen, cover arranged, declared value set, documents archived — filled in before the vessel sails and closed after the goods are received clean. Programs that keep that line rarely need it; when they do, the file is already written, and a transit loss stays what it should be — an insured event with paperwork, not a dispute with a story.
Related Products
Explore products featured in this guide:


Have questions? See our Sizes & Finishes FAQ and Ordering & Certifications FAQ.
Need a custom quote? Send an inquiry or browse our full product catalog.